E-Invoicing 2027: 6 Myths That Could Complicate Your Transition to E-Invoices
Blog
E-invoicing is fast approaching, but it won't catch you off guard. Discover the 6 most common myths about e-invoicing and find out what your company needs to prepare to ensure everything runs smoothly.
E-Invoicing 2027: 6 Myths That Could Complicate Your Transition to E-Invoices
Blog
E-invoicing is fast approaching, but it won't catch you off guard. Discover the 6 most common myths about e-invoicing and find out what your company needs to prepare to ensure everything runs smoothly.
Date: 24.7.2026
|
Posted by: Asseco Solutions
Electronic Invoicing 2027: 6 myths that can complicate your transition to e-invoices
Electronic Invoicing 2027 is approaching, bringing along a lot of questions. Does mandatory e-invoicing also apply to small entrepreneurs? Will a PDF invoice sent by email still be enough? Is it enough if an accountant takes care of everything? And what if a company starts preparing right before January 1, 2027?
Around mandatory electronic invoicing, many myths and misconceptions are arising. Some companies think the change does not concern them at all. Others assume their accountant will handle everything, or that buying a single new tool is enough.
However, reality is a bit more complex. E-invoicing 2027 is not just a new document format. For many companies, it means a change in processes, systems, responsibilities, and the way invoices are created, sent, and processed.
The biggest mistake you can make?
Thinking that electronic invoicing will only be addressed when it becomes mandatory. For smaller companies, preparation can be simple. For more complex business processes, however, it can be a standalone project requiring months of preparation and testing.
Thinking that electronic invoicing will only be addressed when it becomes mandatory. For smaller companies, preparation can be simple. For more complex business processes, however, it can be a standalone project requiring months of preparation and testing.
Myth No. 1: "I am a small entrepreneur. Electronic invoicing 2027 does not concern me."
This is one of the most common misconceptions. Many entrepreneurs think that if they are not VAT payers or issue only a few invoices per month, mandatory e-invoicing will bypass them.
In reality, the change may affect a much wider range of entrepreneurs. It is not just about large companies and VAT payers. It can also be relevant for entrepreneurs who, for example, lease real estate, conduct business with their own assets, or file tax returns and have been assigned a tax identification number (DIČ).
What is changing?
The supplier will no longer need the consent of the other party to receive an electronic invoice. If the invoice is sent in the prescribed manner, the supplier fulfills their obligation.
What does this mean for a small company?
It must be prepared to receive, load, view, and securely store the invoice. Even a small business therefore needs a solution that allows it to process electronic invoices.
For smaller companies, this may not be a complicated project. The important thing is to have a suitable solution for receiving electronic invoices—a so-called digital postman—and a tool in which invoices can be loaded, viewed, and stored.
Myth No. 2: "A PDF invoice by email is an electronic invoice after all. Why wouldn't it be enough?"
This question is asked very often. After all, PDF is an electronic document, so why should the method of invoicing change?
The difference is that electronic invoicing 2027 is not built solely on a visual document intended for human reading. A key role will be played by a structured electronic format, such as XML, which systems can automatically process.
PDF and a structured e-invoice are not the same thing
PDF
It is primarily intended for the visual display of the document. A human can read it, but a system often has to extract data manually or using OCR.
Structured e-invoice
Contains data in a unified structure that enterprise systems can automatically load and further process.
This brings a major change especially for accounting and economic departments. Data such as supplier, customer, items, units of measurement, or payment method can be in a unified format.
The result can be less manual retyping, fewer errors, and less dependence on OCR solutions. E-invoicing 2027 therefore does not have to mean just another obligation. When set up correctly, it can be the beginning of significant automation.
At the same time, however, it is not true that PDF will disappear completely. For certain types of transactions, such as B2C communication or invoicing outside the Slovak Republic, a format suitable for human reading may still be required.
Myth No. 3: "I don't need to deal with e-invoices. After all, I have an accountant."
An accountant can be an important partner in preparing for electronic invoicing. However, it is not possible to fully transfer responsibility for the company to the accountant.
In the event of an audit, the responsible entity is the entrepreneur or legal entity. The accountant may be in charge of processing documents, but the company must have processes set up so that invoices are correctly issued, received, processed, and archived.
A practical question for every company:
If you change your accountant or accounting company tomorrow, do you still have your invoices and documents safely available?
If you change your accountant or accounting company tomorrow, do you still have your invoices and documents safely available?
Electronic invoices will need to be securely stored so that they remain available in the future. At the same time, it is important to know who in the company issues invoices, who approves them, and who ensures they are sent.
Electronic invoicing is therefore not just a topic for accounting. It concerns everyone in the process – from the person recording the delivery of a service or goods, through approvers, to the economic department.
Myth No. 4: "I still have plenty of time until January 2027."
For a small company, preparation can be relatively simple. However, if you have complex supplier-customer relationships, a large volume of invoices, multiple systems, or complex approval processes, the situation is completely different.
It is necessary to check more than just the invoicing system itself. Preparation for mandatory e-invoicing can also affect the ERP system, accounting, codelists, internal approvals, document reception processes, and communication with business partners.
01
Check your systems
Can they create and receive structured electronic invoices?
02
Check your data
Are identifiers, codelists, and business partner data correct?
03
Test processes
Can you approve, issue, and send the invoice in the required time?
At the same time, invoicing requires keeping statutory deadlines in mind. If an invoice in a company is first approved, checked, and waiting for the statutory representative's signature, each step can affect whether the invoice is issued on time.
Therefore, pilot operation and testing with key suppliers or customers can be very useful. The company can test how electronic document exchange will work even before the go-live transition.
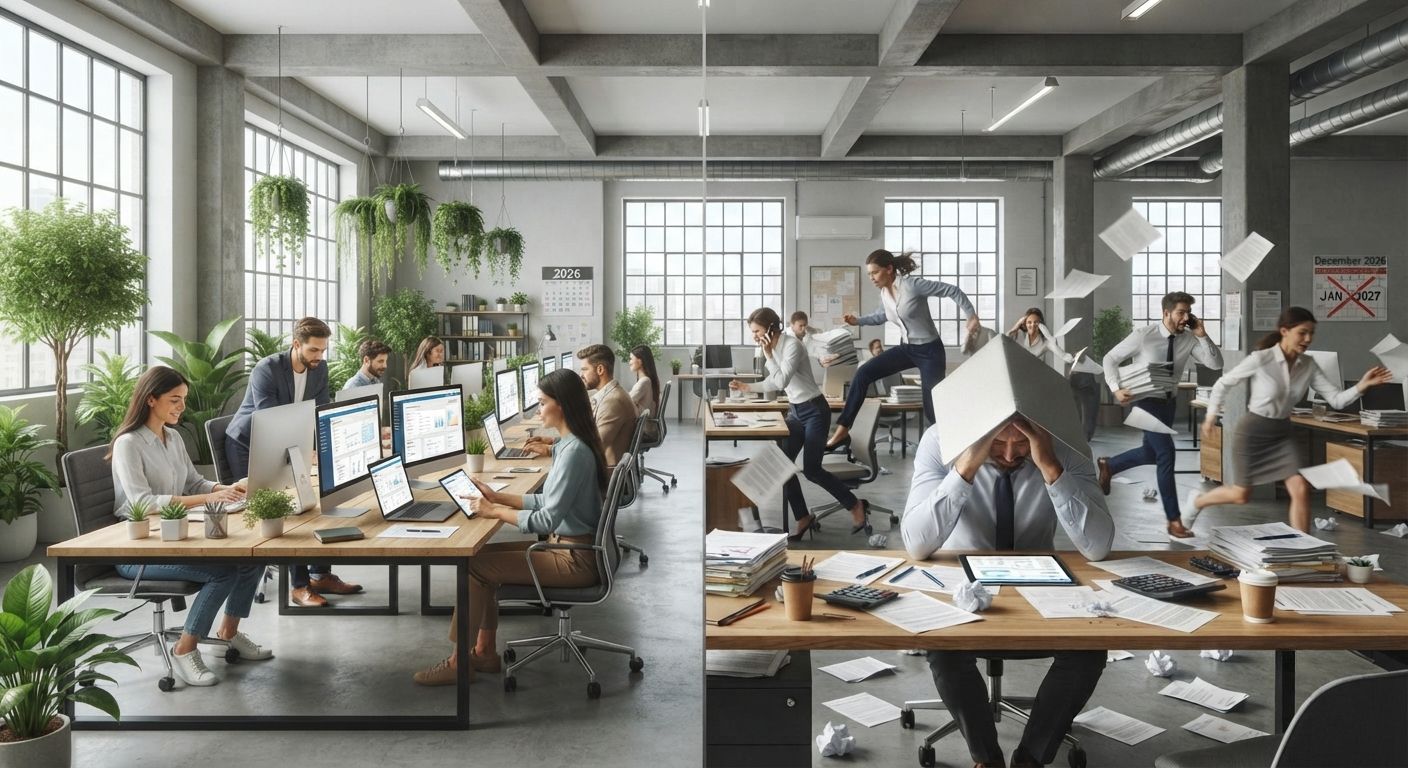 Address the transition to the e-invoice in time and avoid December panic. The capacities of consultants ensuring the transition are limited.
Myth No. 5: "After sending the invoice, I will simply correct it."
Electronic invoicing also brings a change in how errors on issued documents are handled.
Once an invoice is sent into the network, its values cannot be handled in the same way as a document that remained only in the internal system. In the case of significant errors, it may be necessary to cancel the original document and issue a new one.
This means that the correctness of data before sending will be even more important. The company must clearly define who checks the invoice and who can approve it.
The more invoices a company issues, the greater the importance of a quality process before sending.
An error at the beginning can mean extra administration, document correction, and potential complications during processing.
An error at the beginning can mean extra administration, document correction, and potential complications during processing.
Myth No. 6: "E-invoicing will just be another cost."
If we look at electronic invoicing merely as an obligation, of course it can act as an additional cost.
However, when set up correctly, it can bring the exact opposite effect. Structured data allows invoices to be better linked with orders, requisitions, and other business processes.
The economic department therefore does not have to spend time manually retyping data from invoices. Most of the work can be automated, and people can focus on control, analysis, and financial management.
From obligation to opportunity
The greatest potential of electronic invoicing is not just that the invoice is sent electronically. Real value is created when invoice data is automatically linked with other processes in the company.
Is buying a single tool enough? Not always.
One common misconception is that preparing for electronic invoicing 2027 simply means buying one new tool.
In reality, the entire process must be taken into account. A company may need a solution for the electronic transmission of invoices, but it must also review its existing invoicing or enterprise system.
What questions should you definitely ask?
- Can your system create an electronic invoice in the required format?
- Can it load and process a received e-invoice?
- Can the system be connected to the digital postman?
- Is your customer and supplier data correct?
- Do you have internal approval processes set up?
- Do you know who in the company will be responsible for the entire process?
What should a company do as a first step?
The best start is not to buy a new system immediately. The first step is to map the current state.
1. Map invoicing
Uncover where and how invoices are created and received in the company.
2. Review systems
Find out which systems will need to be updated or connected.
3. Set up processes
Review deadlines, approvals, responsibilities, and archiving.
4. Choose a solution
Identify a suitable method for electronically sending and receiving invoices.
Electronic invoicing 2027 doesn't have to be chaos
For a small entrepreneur, the transition to electronic invoicing can be relatively simple. For medium and larger companies, however, it can be a complex change that affects multiple departments.
The important thing is not to start addressing just the invoice itself. You need to look at the entire process – from the creation of the order or delivery of the service, through approval and issuance of the document, to its electronic sending, reception, processing, and archiving.
If you start in time, you can not only comply with the process, but also simplify and automate it at the same time. Countries that have already transitioned to electronic invoicing report up to a 50 percent savings in time spent on invoicing.
Don't know how your company is doing?
Preparation for mandatory electronic invoicing 2027 does not have to start with the purchase of a new system. It starts with answering a simple question: Do we know everything our company will need to change?
If you are not sure where to start, contact us. Through the E-Invoice Readiness Analysis we will help you map your invoicing processes, used systems, and areas that require preparation for the e-invoice.
✔ We will map the current state
✔ We will identify risks
✔ We will recommend the next steps